Debt Avalanche vs Snowball Explained: Which Payoff Strategy is Best?
Paying off multiple debts can feel overwhelming. The Debt Avalanche and Debt Snowball methods are two proven strategies to eliminate balances systematically. Here is the math behind each approach. See exactly how fast you can become debt-free with our debt snowball calculator.
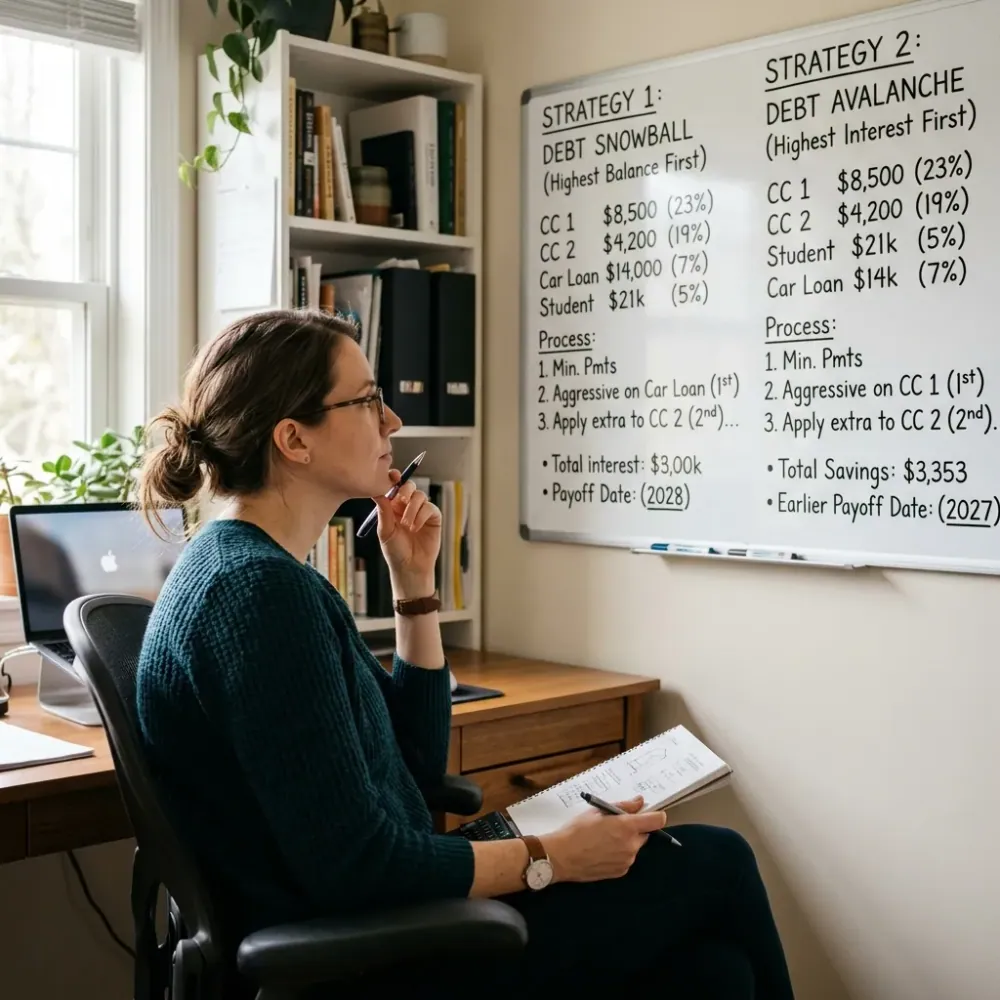
What is the Debt Snowball Method?
Popularized by financial commentators, the Debt Snowball method focuses on psychological wins. You list all your debts from smallest balance to largest balance, regardless of the interest rate.
You make minimum payments on all debts except the smallest one. Every extra dollar in your monthly budget goes toward wiping out that smallest balance. Once the smallest debt is gone, you take the money you were paying on it and roll it into the next smallest balance.
What is the Debt Avalanche Method?
The Debt Avalanche method focuses purely on mathematics and saving money. You list your debts from the highest interest rate to the lowest interest rate.
Again, you pay the minimums on everything, but you aggressively attack the debt with the highest APR first. The Federal Trade Commission (FTC) generally advises prioritizing high-interest debts because they cost you the most money every day you carry a balance.
Which One Should You Choose?
If you are highly disciplined and want to save the absolute maximum on interest charges, use the Avalanche. If you struggle with motivation and need to see accounts hit $0 quickly to feel progress, use the Snowball.
You can also test both scenarios using our free Debt Payoff Calculator to see exactly how much money and time you will save with each strategy. For some, the interest savings of the Avalanche is just a few hundred dollars, making the psychological boost of the Snowball worth the extra cost.
Step-by-Step Scenario: Avalanche vs. Snowball
Let us look at a realistic household debt profile. Imagine you have exactly $800 a month to dedicate to debt repayment, and you are carrying the following three balances:
- Credit Card A: $2,000 balance at 24% APR (Minimum payment: $60)
- Car Loan: $8,000 balance at 6% APR (Minimum payment: $250)
- Credit Card B: $5,000 balance at 18% APR (Minimum payment: $150)
Your total minimums equal $460. Because you have $800 budgeted, you have a "$340 extra" weapon to deploy every month.
Executing the Debt Snowball
Under the Snowball method, you ignore the interest rates entirely. You rank the debts by size: Card A ($2,000), Card B ($5,000), Car Loan ($8,000). You pay the minimums on Card B and the Car Loan, and throw your entire $340 extra at Card A. Within just a few months, Card A is completely destroyed. You take that freed-up $60 minimum, add it to your $340 extra, and unleash a $400 avalanche onto Card B. You get an immediate psychological victory, which keeps you motivated.
Executing the Debt Avalanche
Under the Avalanche method, you rank by mathematical damage: Card A (24%), Card B (18%), Car Loan (6%). Coincidentally, in this specific scenario, Card A is both the highest interest rate and the smallest balance. You attack Card A first. But if Card B had the 24% rate, you would attack the $5,000 balance first, even though it would take longer to see a completely closed account. This method saves you the most money in interest charges.
Crucial Mistakes to Avoid
Another massive error is attempting either of these strategies without an emergency fund in place. If you aggressively throw every spare dollar at your debt and your car breaks down, you will be forced to swipe the credit card again, completely demoralizing your progress. Always save a starter emergency fund before attacking debt. You can calculate exactly how much you need using an emergency fund calculator.
Finally, do not confuse these strategies with restructuring. If your interest rates are above 20%, neither the snowball nor avalanche can outpace the math of a brutal APR. In those cases, you must look into balance transfers to temporarily freeze the interest while you execute your payoff plan.
Frequently Asked Questions (FAQs)
Does debt consolidation work with these methods?
Yes. Taking out a consolidation loan combines your debts into one monthly payment, often at a lower interest rate. If you consolidate, you only have one balance to focus on, simplifying the process entirely. You can use a debt consolidation calculator to see if it makes financial sense for you.
Which method pays off debt faster?
The Debt Avalanche method always pays off debt faster mathematically because you are eliminating the compounding effect of the highest interest rates early on. However, if you abandon the plan due to lack of motivation, the Snowball might be practically faster for you.
