What is an Appraisal?
In real estate, an appraisal is an unbiased, professional assessment of a property's fair market value. When you apply for a dti calculator to buy or refinance a house, the bank will order an appraisal to ensure the property is actually worth the amount of money you are asking to borrow. For additional context, read about collection agency and calculate your own numbers using our collateral in banking and lending. You might also find our guide on prepayment penalty in lending helpful.
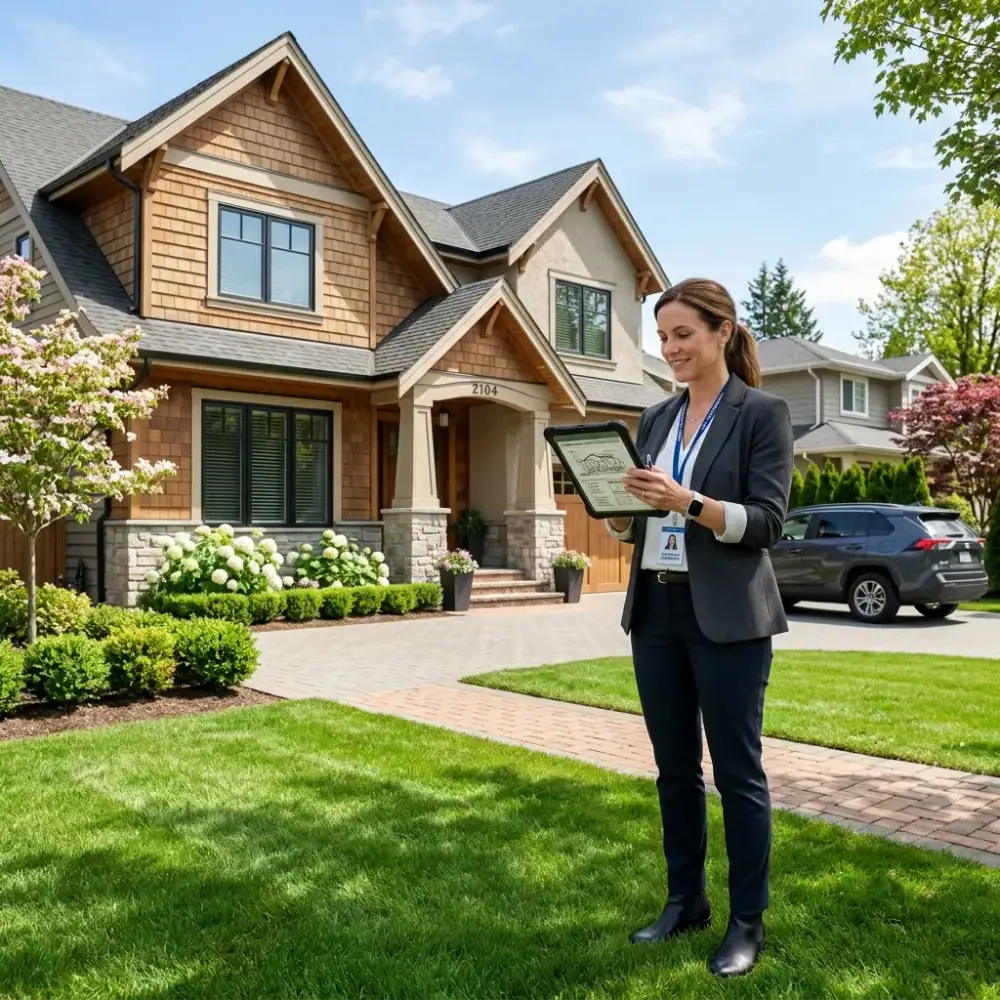
Why Do Lenders Require Appraisals?
A bank's primary concern when issuing a mortgage is risk. The home itself serves as collateral for the loan. If you default on your mortgage and the bank is forced to foreclose, they need to know they can sell the property to recoup their money. To learn more about your rights regarding property valuations during the mortgage process, visit the Consumer Financial Protection Bureau.
If you agree to buy a house for $500,000, but the appraiser determines it is only worth $400,000, the bank will refuse to lend you the full $500,000. They will not risk lending more than the home's true market value.
How is the Value Determined?
A licensed, independent appraiser conducts the evaluation using a combination of on-site inspection and historical data. They look at two main factors:
- Property Condition: The appraiser will visit the home to inspect the structural integrity, square footage, number of bedrooms and bathrooms, lot size, and any recent upgrades or noticeable defects.
- Real Estate Comparables ("Comps"): The most critical part of an appraisal is comparing the target home to similar properties in the exact same neighborhood that have sold within the last three to six months.
What is an Appraisal Gap?
An appraisal gap occurs when the appraiser values the home for less than your agreed-upon purchase price. This frequently happens in highly competitive real estate markets where buyers are bidding up prices.
If there is an appraisal gap, the bank will not cover the difference. You have three options: you can renegotiate the price with the seller, you can walk away from the deal (if you have an appraisal contingency in your contract), or you must pay the cash difference out of your own pocket on closing day.
Frequently Asked Questions (FAQs)
Is an appraisal the same as a home inspection?
No. An appraisal is for the lender to confirm the financial value of the home. A home inspection is for the buyer to find out if the home has hidden defects (like a broken HVAC, termite damage, or a leaking roof). Appraisers look for general condition, while inspectors look for specific, costly flaws.
