What is an Independent Contractor?
An independent contractor is a self-employed individual or business that provides services to another entity under the terms of a contract. Unlike traditional employees, they are not on the company payroll for payroll taxes, making understanding the classification of an independent contractor versus an employee essential for accurately filing taxes and managing business operations. Misclassifying workers can lead to severe penalties from tax authorities, owed back taxes, and legal disputes.
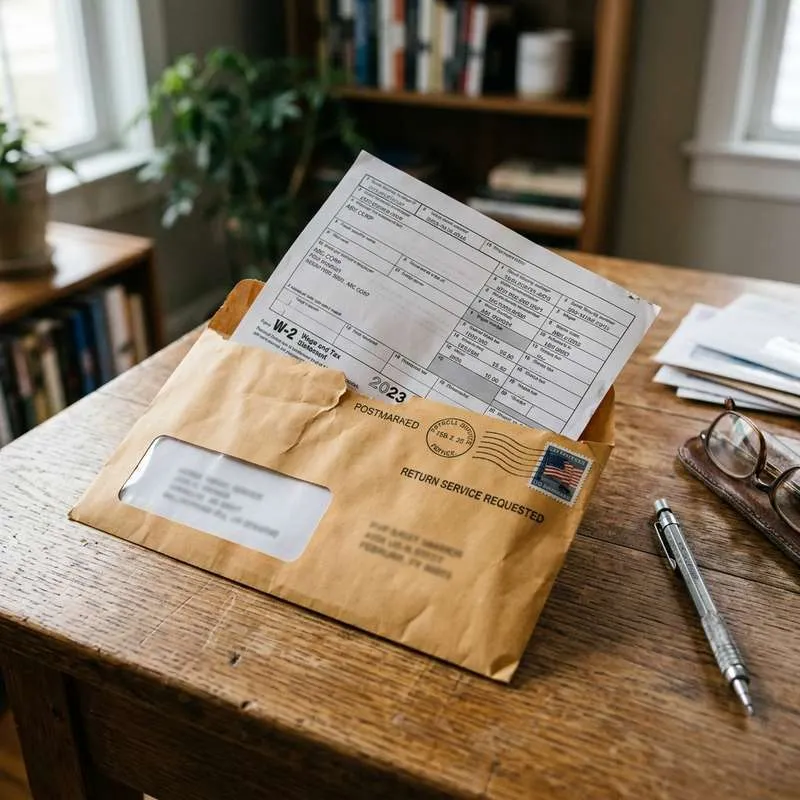
The IRS Definition: 1099 vs W-2
According to the IRS, an individual is an independent contractor if the payer has the right to control or direct only the result of the work and not what will be done and how it will be done. This means the worker retains independence over the methodology, scheduling, and execution of the requested project.
Independent contractors operate as their own separate business entities, such as a sole proprietorship or an LLC. Because they are not employees, they do not have payroll taxes automatically withheld from their compensation. Instead, they are entirely responsible for calculating and paying their own taxes, including hard inquiry, which covers both the employer and employee portions of Medicare and Social Security. At the end of the tax year, an independent contractor receives a 1099 Form (most commonly a 1099-NEC for non-employee compensation) detailing their earnings from each client that paid them more than $600 during the year, unlike traditional employees who receive a inflation.
Common Law Rules: Behavioral and Financial Control
To determine whether a worker is an independent contractor or an employee, the IRS evaluates the relationship based on three main categories of evidence: Behavioral Control, Financial Control, and the Type of Relationship. No single factor determines a worker's status; instead, the entire relationship must be considered.
- Behavioral Control: Does the company control or have the right to control what the worker does and how the worker does their job? An independent contractor generally decides when, where, and how the work is completed. They may use their own specific processes or software rather than being forced into the company's mandated workflow.
- Financial Control: Are the business aspects of the worker’s job controlled by the payer? This includes how the worker is paid, whether expenses are reimbursed, and who provides tools or supplies. An independent contractor is more likely to have unreimbursed business expenses, invest in their own equipment, and have the ability to realize a profit or incur a loss on a specific job.
- Type of Relationship: Are there written contracts detailing the nature of the relationship? Does the worker receive employee-type benefits, such as a pension plan, health insurance, or paid vacation? The permanency of the relationship is also a major factor—independent contractors are often hired for specific projects or temporary periods, whereas employees are generally hired indefinitely.
A true independent contractor often invests heavily in their own equipment and markets their services to the general public. If a business dictates a strict 9-to-5 schedule, provides a laptop and company email, and prohibits the worker from taking on other clients, the worker is likely an employee, regardless of any independent contractor agreement they may have signed.
Worked Example & Behavioral Tips
To understand the distinction in practice, consider how businesses interact with service providers on a daily basis. Maintaining clear boundaries is essential to pass an IRS classification audit.
