How to Choose the Right Student Loan Repayment Plan
When you graduate college, the federal government automatically places you on the Standard 10-Year Repayment Plan. For many borrowers, accepting this default option is a massive financial mistake. Choosing the right repayment plan depends entirely on your income trajectory, your total debt balance, and whether you qualify for government forgiveness programs. This guide breaks down exactly how to evaluate your options so you do not overpay by tens of thousands of dollars. For official details on all available options, you can review the Federal Student Aid repayment plans guide.
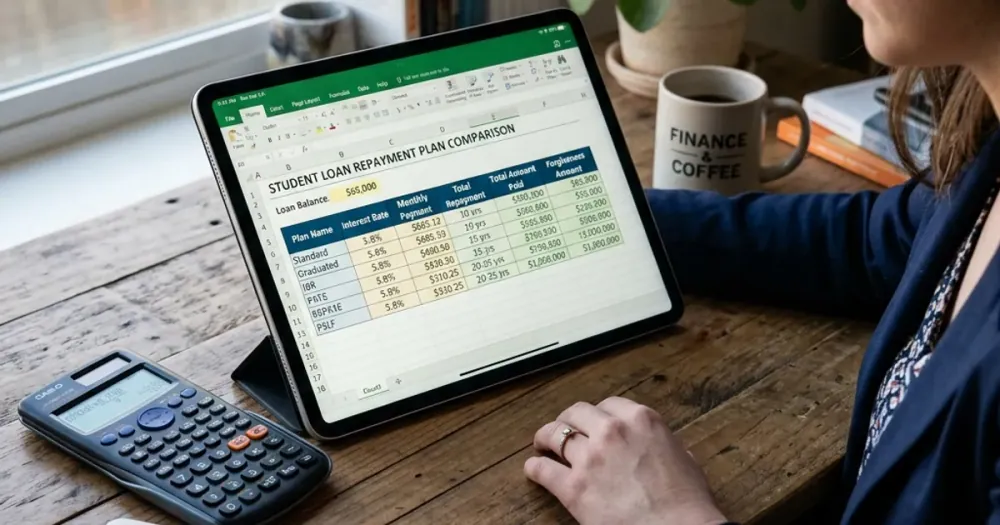
1. The Standard 10-Year Plan (The Aggressive Route)
The Standard Plan divides your total loan balance and projected interest into 120 equal monthly payments. If you make every payment, you are guaranteed to be debt-free in exactly ten years.
Who it is for: This plan is ideal for high-income earners who have a relatively low student loan balance (e.g., you earn $80,000 a year but only have $25,000 in debt). It is also the best mathematical option if your primary goal is to minimize the total amount of interest you pay to the government over the life of the loan.
If you want to be even more aggressive, you can stay on the Standard Plan and make extra principal payments. You can use our Student Loan Payoff Calculator to see how adding just $100 or $200 extra a month can shave years off your repayment timeline and save you thousands in interest.
2. Income-Driven Repayment (The Safety Net)
If your student loan balance is higher than your annual salary, the Standard 10-Year payment will likely consume too much of your paycheck. This is where Income-Driven Repayment (IDR) plans become essential. The federal landscape offers the Repayment Assistance Plan (RAP) for loans made on or after July 1, 2026, and Income-Based Repayment (IBR) for existing loans (the SAVE plan ended in March 2026, and PAYE/ICR borrowers must switch by July 1, 2028). These plans calculate your monthly payment based on your income, family size, or dependents rather than your debt balance.
Lower Monthly Payments: Under IBR, payments are capped at 10% (for new borrowers on or after July 1, 2014) or 15% (for older borrowers) of your discretionary income above 150% of the poverty guideline. Under RAP, payments follow graduated income bands with a $50 monthly deduction per dependent and a $10 minimum. If your income drops below the threshold, your payment can be as low as $0 under IBR or $10 under RAP. You can run your exact numbers through our IDR Payment Calculator.
The Forgiveness Factor: IDR plans establish structured forgiveness timelines: 20 years for newer IBR borrowers, 25 years for older IBR borrowers, and 30 years (360 payments) under RAP. If you make qualifying payments for that entire duration, the federal government legally forgives any remaining balance. Furthermore, you must be enrolled in an eligible income-driven plan if you are pursuing Public Service Loan Forgiveness (PSLF), which forgives your debt tax-free after just 10 years (120 payments) of qualifying public service work.
3. Graduated and Extended Plans
If you do not qualify for a low payment under an IDR plan (perhaps because your income is too high) but you still cannot afford the Standard 10-Year payment, the government offers two alternative structures:
Graduated Repayment Plan: This plan starts with very low monthly payments that automatically increase every two years. The assumption is that your salary will naturally increase over time, allowing you to afford the higher payments later. The loan is still paid off in 10 years, but you will pay more total interest than the Standard Plan.
Extended Repayment Plan: If you owe more than $30,000 in federal loans, you can extend your repayment timeline from 10 years to 25 years. This slashes your monthly payment, but unlike IDR plans, there is no forgiveness at the end. You will pay the debt in full, and because the timeline is stretched to 25 years, the total interest paid will be massive.
4. The Refinance Strategy (Private Loans)
If you have a high income, excellent credit, and you want to escape high federal interest rates, refinancing is a viable strategy. Refinancing involves a private bank (like SoFi, Earnest, or Laurel Road) paying off your federal loans and issuing you a new private loan at a lower interest rate.
However, you must be extremely cautious. Refinancing federal loans into private loans permanently strips away your access to IDR plans, federal forbearance, and all forms of student loan forgiveness. You must understand the deep legal differences between federal vs. private student loans before signing a new contract.
Generally, you should only learn when to refinance student loans if your job is hyper-secure, you have a 6-month emergency fund, and you have zero intention of ever relying on government forgiveness programs.
Frequently Asked Questions (FAQs)
Can I switch my federal repayment plan later?
Yes. With federal student loans, you are never locked into a single plan permanently. You can change your repayment plan at any time, for free, by logging into your StudentAid.gov account or contacting your loan servicer.
Do IDR plans hurt my credit score?
No. Enrolling in an Income-Driven Repayment plan does not negatively impact your credit score. As long as you make your newly calculated IDR payment on time every month, it is reported to the credit bureaus as a standard on-time payment.
What if I overpay on an IDR plan?
If you pay more than your required monthly IDR amount, the extra money generally goes toward any outstanding interest first, and then directly to the principal balance. However, if your ultimate goal is loan forgiveness (like PSLF), overpaying is mathematically a bad idea, as you are just giving the government money that would have been forgiven anyway.
